How to Do Payroll for a Small Business (Step-by-Step Guide)
Doing payroll right the first time
Payroll is the one task where small errors compound fast: a misclassified worker, a missed filing deadline, or a wrong deduction can turn into penalties, back taxes, and unhappy employees. The good news — payroll follows a fixed, repeatable cycle. This guide walks through it step by step for a US small business.
Step 1: Choose your pay schedule
Pick one schedule and keep it: weekly, biweekly (every two weeks — the most common in the US), semi-monthly (twice a month), or monthly. Biweekly means 26 paydays a year; semi-monthly means 24. Your state may restrict the options — some require paychecks at least semi-monthly or biweekly. Once chosen, put every payday on the calendar for the whole year, including the tax deposit dates that follow each one.
Step 2: Collect the paperwork before day one
- Form W-4 from every employee — it determines federal income tax withholding.
- Form I-9 to verify work eligibility (keep it on file, do not send it anywhere).
- State withholding form where applicable.
- Direct deposit details and a signed authorization.
Collect these before the first paycheck, not after. Retro-correcting withholding is painful for everyone.
Step 3: Classify workers correctly
Employees and independent contractors are not interchangeable labels. Control over how, when, and where work is done points to employment; genuinely independent businesses with multiple clients and their own tools point to contracting. Misclassifying employees as contractors to skip payroll taxes is one of the most expensive mistakes a small business can make — the IRS can recover years of back employment taxes, penalties, and interest. When in doubt, use the IRS common-law test or talk to your accountant before paying.
Step 4: Calculate gross pay
Hourly employees: hours worked × hourly rate. Under the Fair Labor Standards Act, non-exempt employees earn overtime — at least 1.5× their regular rate — for hours beyond 40 in a workweek. "Salary" does not automatically exempt someone from overtime; duties and pay level determine that.
Salaried employees: annual salary ÷ number of pay periods. A $52,000 salary on a biweekly schedule is $2,000 gross per paycheck.
Also decide how you handle bonuses, commissions, tips, and paid time off — and write it down in a one-page policy so nobody improvises.
Step 5: Apply deductions in the right order
From gross pay, subtract:
- Pre-tax deductions: Section 125 health premiums, traditional 401(k) contributions — these reduce taxable wages.
- Federal income tax withholding per each employee's W-4 (use the IRS Publication 15-T methods or payroll software).
- FICA: 6.2% Social Security + 1.45% Medicare withheld from the employee — and you match both amounts as the employer (Social Security applies up to the annual wage base; Medicare has no cap).
- State and local taxes where applicable.
- Post-tax deductions: Roth 401(k), garnishments, union dues.
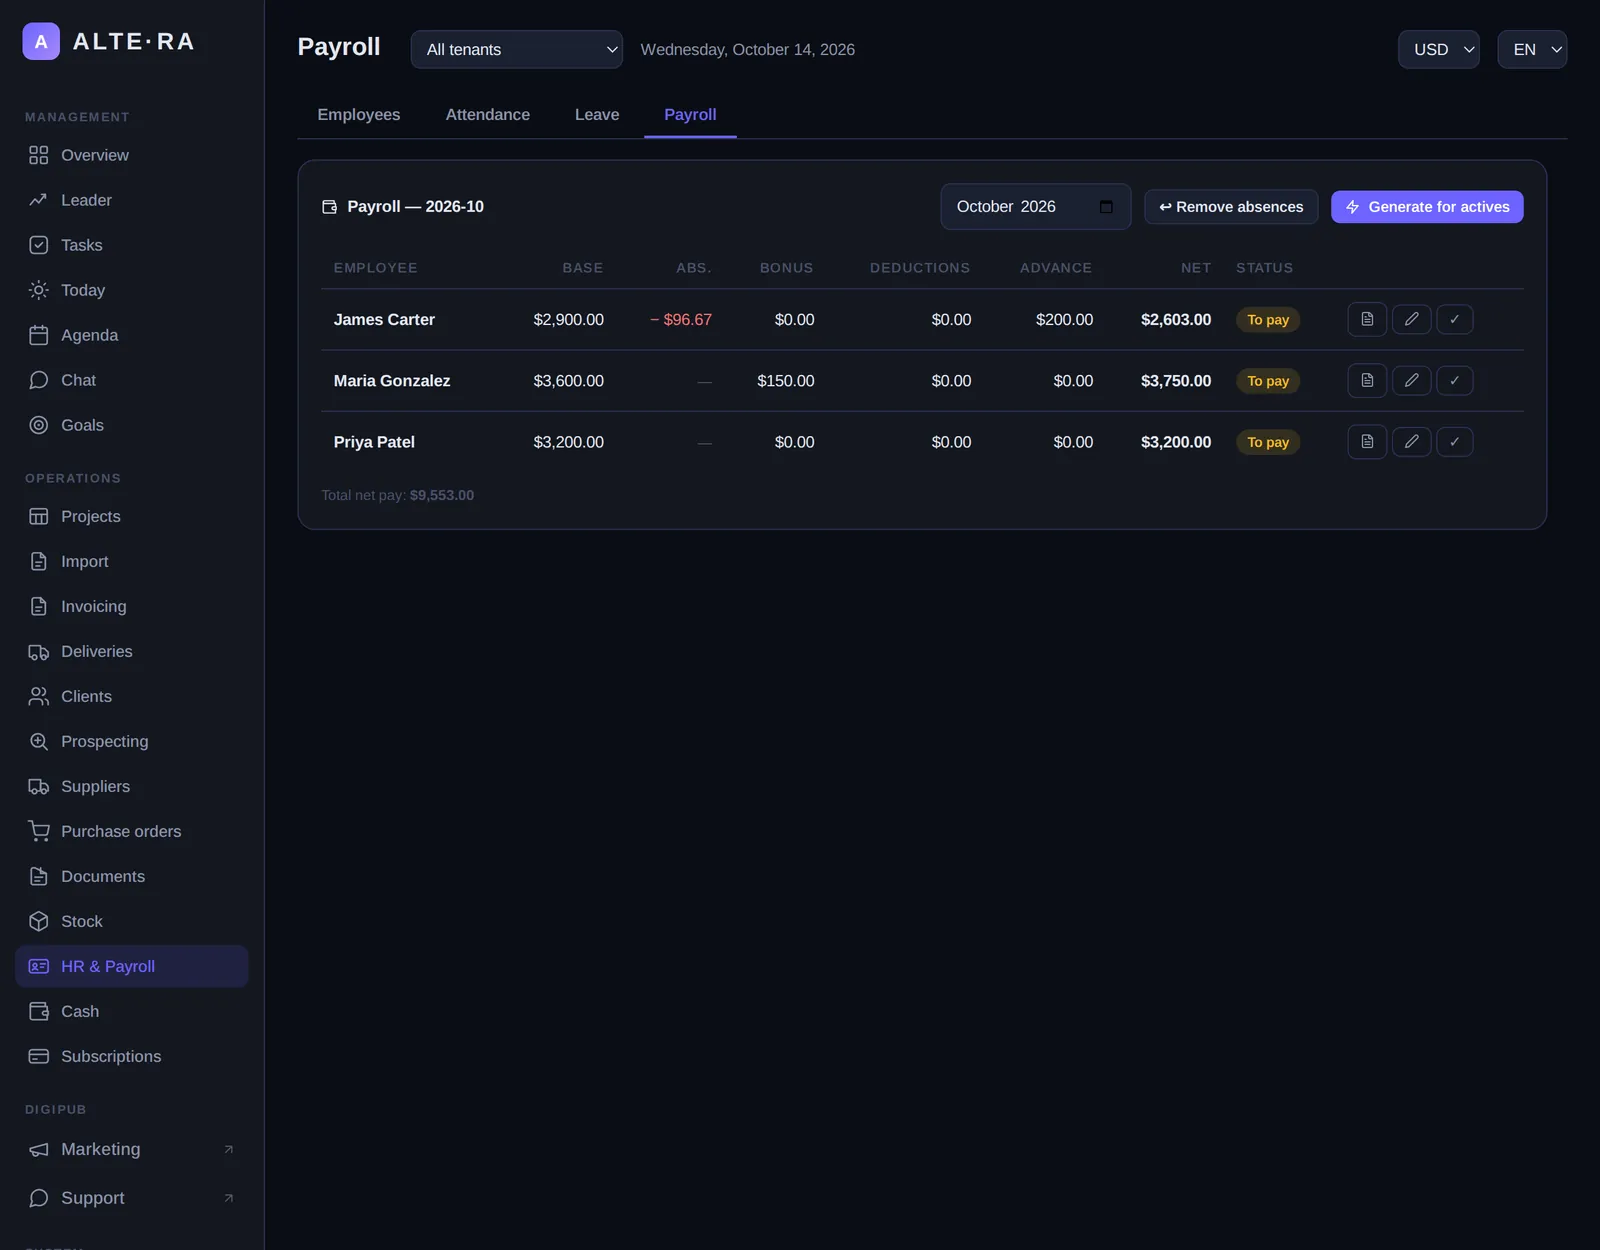
What remains is net pay — the number on the paycheck. As the employer, you also pay unemployment taxes (FUTA and state SUTA) that come out of company money, not employee pay.
Step 6: Pay your team and deliver pay stubs
Direct deposit is the norm — schedule the transfer 1–2 business days before payday so funds land on time. Provide a pay stub (electronic is fine in most states, some require printed) showing gross pay, each deduction, and net pay. Several states — including California and New York — have specific pay stub content requirements; check yours.
Step 7: Deposit taxes and file on schedule
- Deposit federal payroll taxes on your assigned schedule — monthly or semi-weekly — via EFTPS. Late deposits trigger automatic penalties.
- File Form 941 quarterly (or Form 944 annually if eligible) reporting withheld taxes.
- File Form 940 annually for FUTA.
- Issue W-2s by January 31 each year, plus W-3 to the SSA and state reconciliations.
- Keep payroll records at least 4 years (IRS requirement).
Common payroll mistakes to avoid
- Missing a tax deposit deadline — penalties start small and grow fast; trust-amount penalties can reach 100%.
- Missing overtime — the most frequent wage claim. Track hours, not memory.
- Misclassifying contractors — see step 3; this is the expensive one.
- Forgetting employer-side taxes — FICA match and unemployment taxes are your cost, and they must be budgeted on top of gross wages (typically 8–12% extra).
- Off-the-books "advances" — loans and advances must be documented and repaid through payroll deductions properly, or they become taxable gifts and payroll headaches.
- Skipping final paychecks rules — each state sets its own deadline for paying a departing employee; some require it on the last day.
A realistic alternative to manual payroll
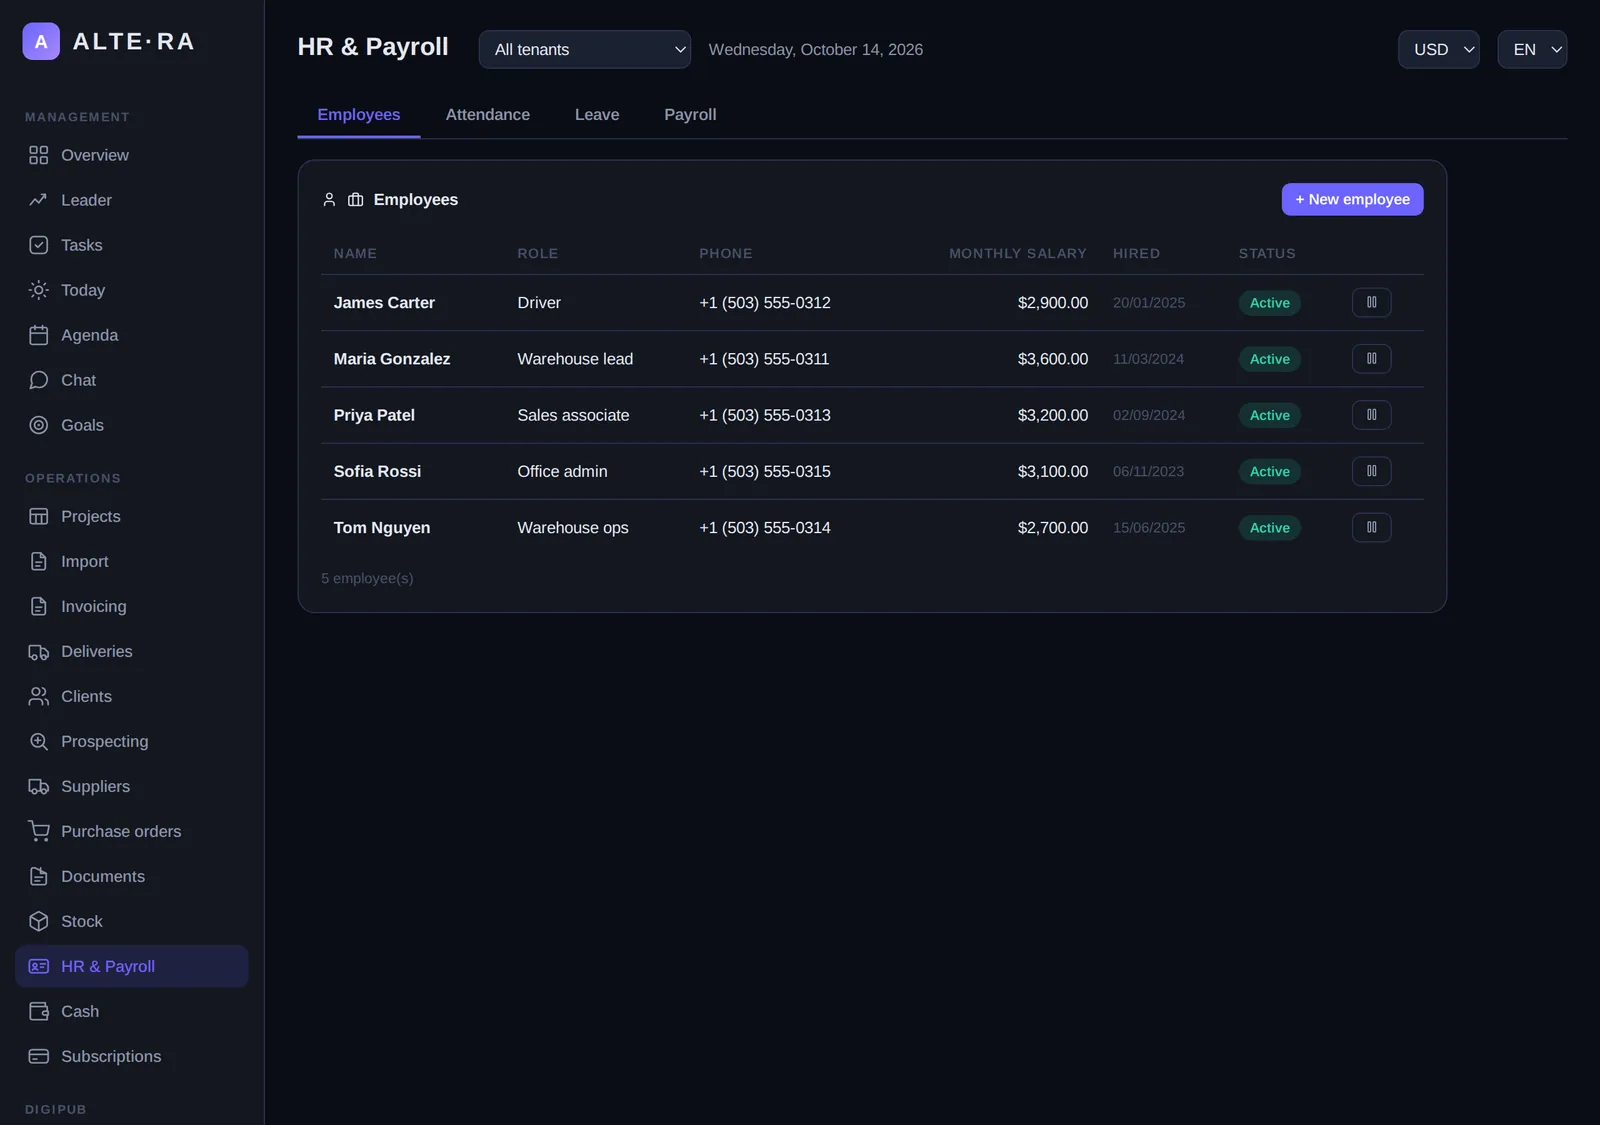
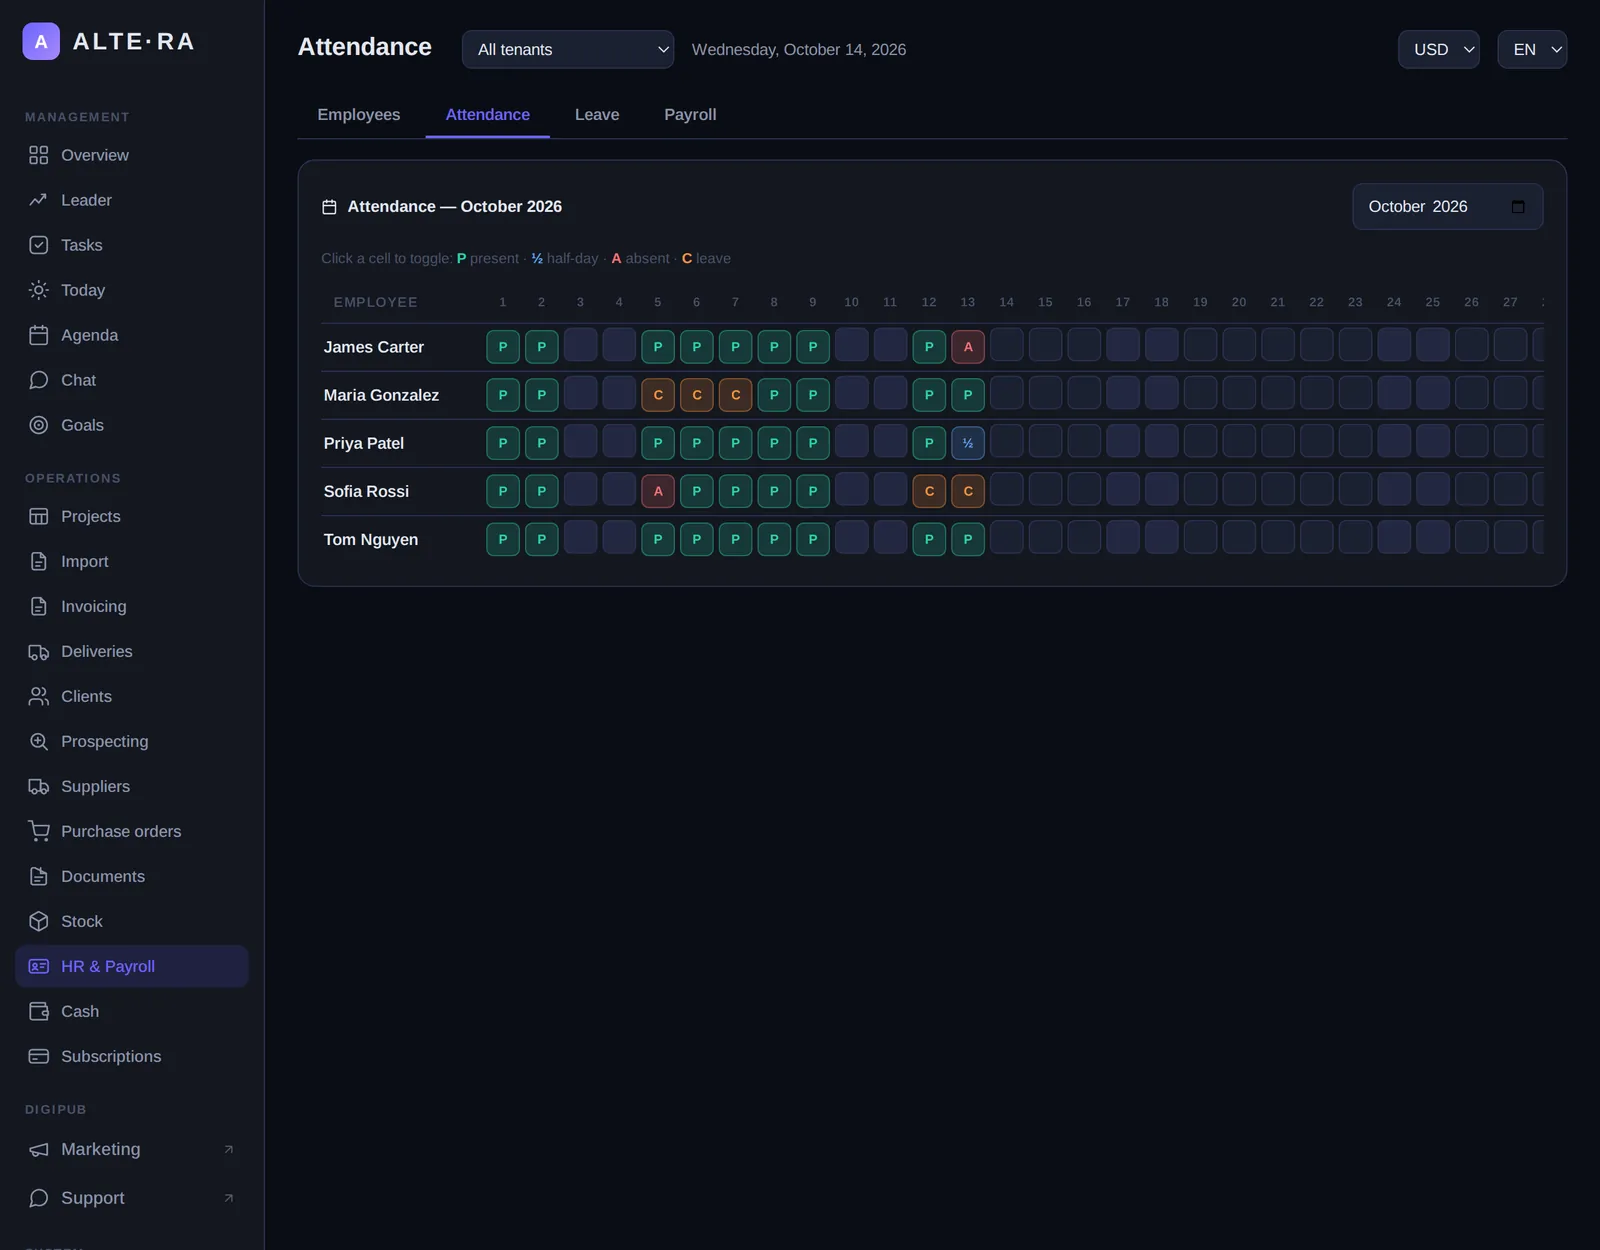
Doing payroll by spreadsheet works for one or two people — until overtime rules, quarterly filings, and advances make it fragile. Altera's HR & Payroll module was built for small teams: active employee records, a monthly attendance grid (present / half-day / absence / leave), and pay runs with bonuses, deductions, and advances that compute net pay automatically — inside the same tool running your invoices, clients, and stock. Try Altera free and run your next pay period on it.
FAQ
How much does it cost an employer beyond gross wages?
Plan for roughly 8–12% on top of gross pay: employer FICA match, federal and state unemployment insurance, workers' compensation, and any benefits you fund.
Can I just pay someone as a contractor to avoid payroll?
Only if the relationship is genuinely independent. Misclassification is one of the costliest mistakes in small business payroll — back taxes, penalties, and interest can be recovered over multiple years.
What payroll records must I keep, and for how long?
Keep time cards, wage calculation records, tax deposits, and filings for at least 4 years under IRS rules; some states require longer.
Biweekly or semi-monthly — does it matter?
Biweekly (26 checks) is easier for hourly teams and overtime tracking; semi-monthly (24 checks) aligns with monthly cycles but complicates weekend paydates. Both are common; check your state's minimum frequency rules first.